

Understanding a 3-2-1, 2-1, and 1-0 Buydown Mortgage is extremely important in the 2023 housing market with elevated rates and lower affordability.
Before choosing this financing option, consider the signs you are ready to buy a house, including whether you can comfortably afford the monthly payments after the temporary rate reduction ends and whether the upfront buydown cost fits your budget.
Understanding 3-2-1 Buydown Mortgage
A 3-2-1 buydown mortgage starts at 3% lower than your note rate in year 1, 2% lower in year 2, and 1% lower in year 3. So, if you get a rate of 6%, your first-year monthly payment will be calculated at 3%, second year at 4%, third year at 3%, and then goes back to your note rate (i.e. 6%) for the rest of the term of the loan.
Let’s look at an example – Say your loan amount is $500,000 at a note rate of 6%. Let’s also assume that the yearly property tax is $7,000 and the homeowner’s insurance is $1000/year. For the 1st year, your monthly payment will be at 3%. See the chart below for the breakdown.
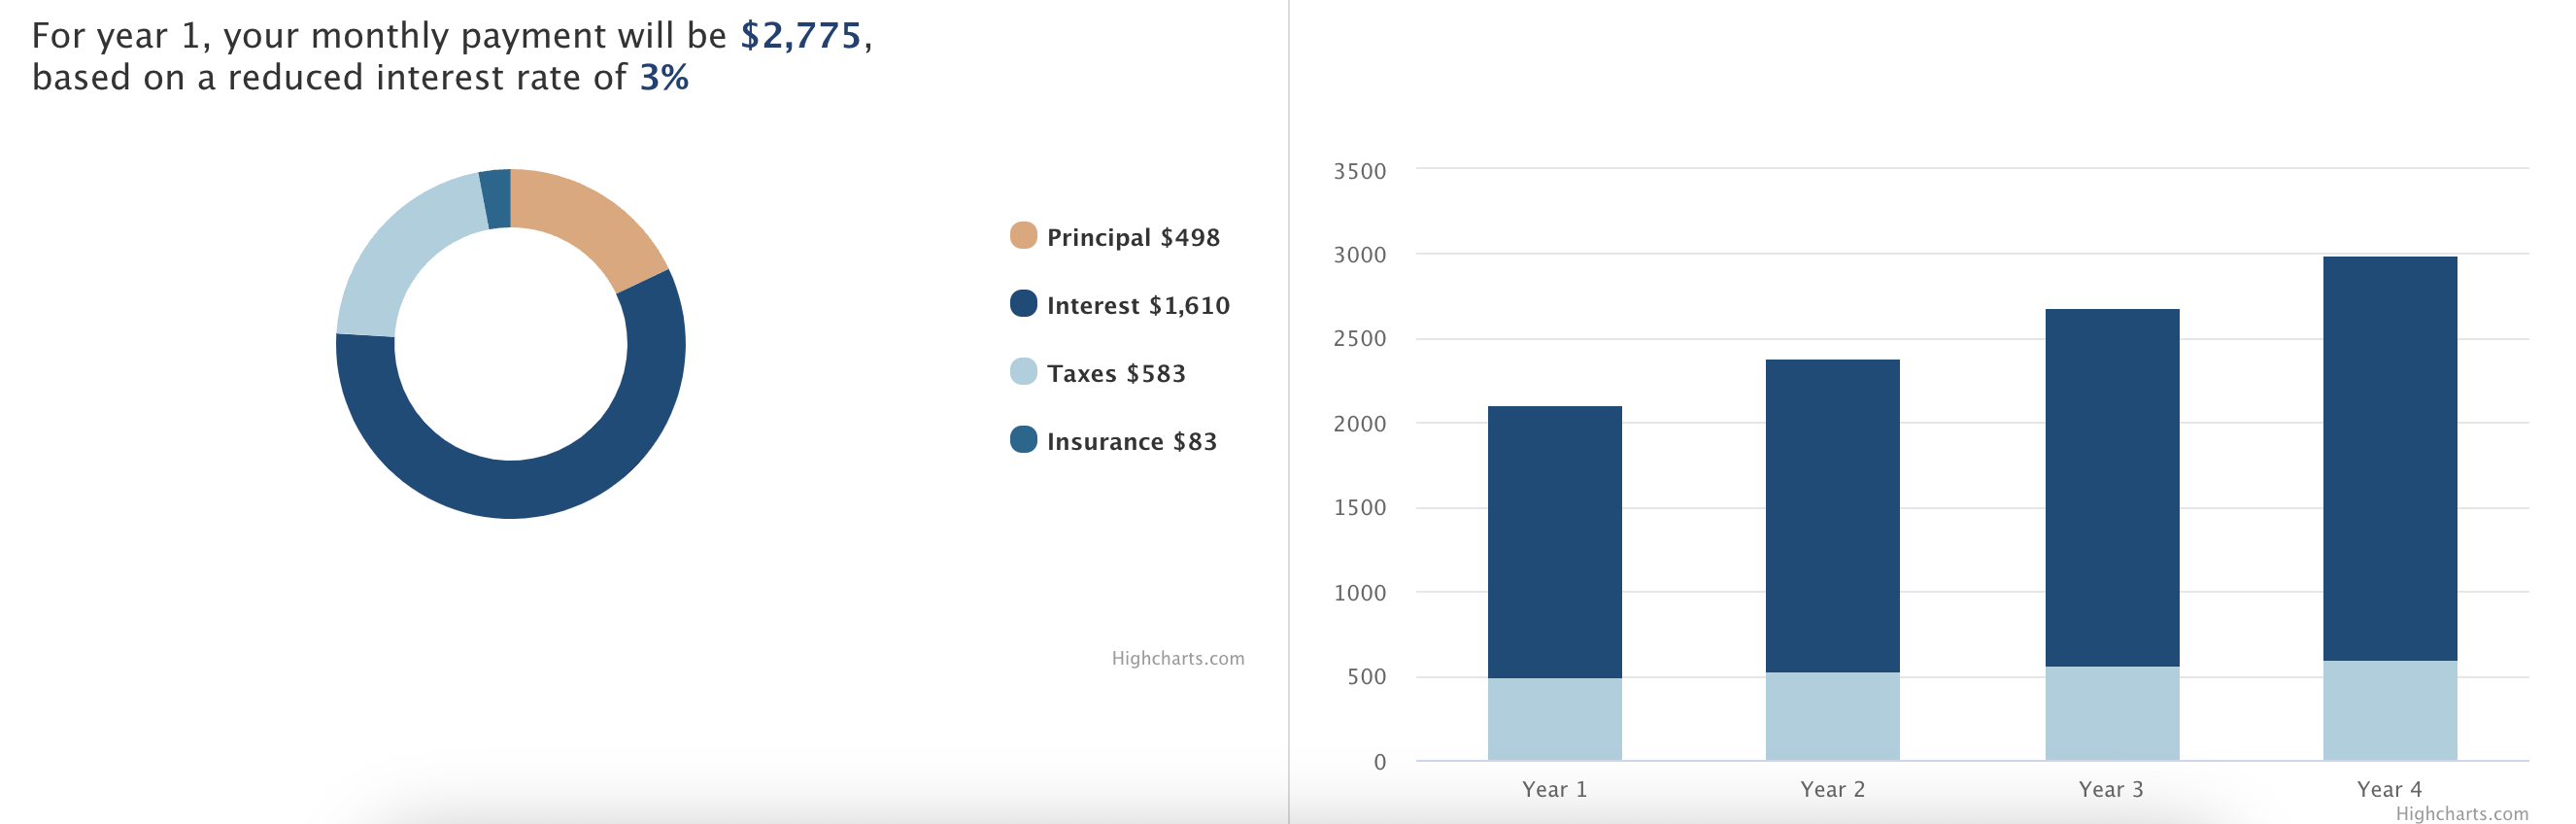
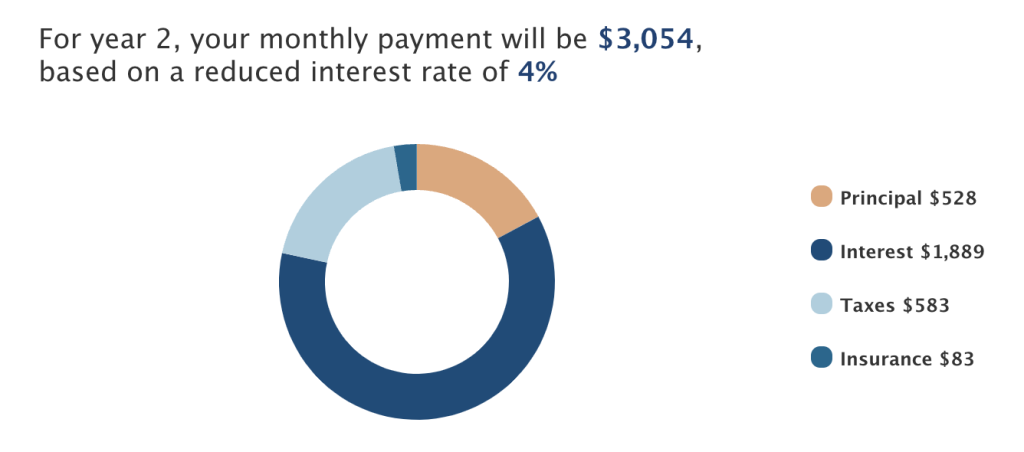

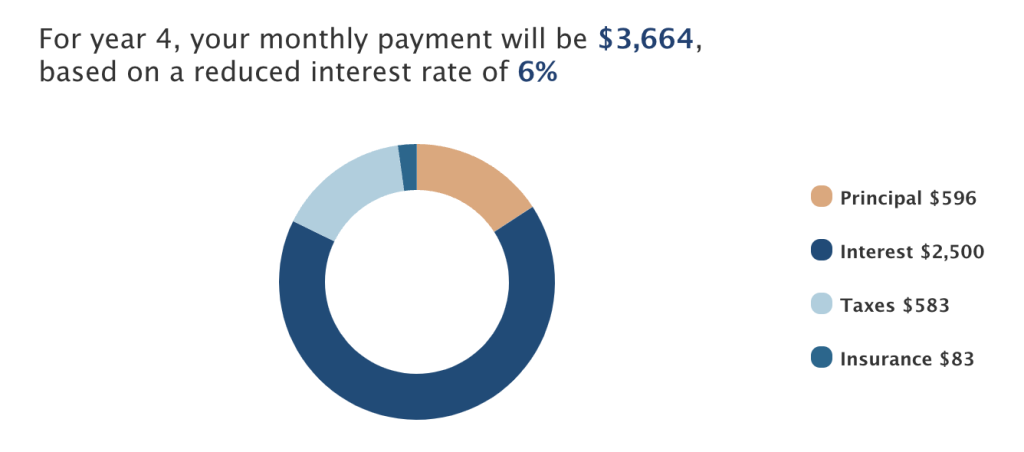
Run your customized calculation using our buydown mortgage calculator
Understanding 2-1 Buydown Mortgage
A 2-1 buydown mortgage starts at 2% lower than your note rate in year 1, and 1% lower in year 2. So, if you get a rate of 6%, your first-year monthly payment will be calculated at 4%, your second year at 5%, and then goes back to your note rate (i.e. 6%) for the rest of the term of the loan.

Your Personalized Rate
Let’s look at an example – Say your loan amount is $500,000 at a note rate of 6%. Let’s also assume that the yearly property tax is $7,000 and the homeowner’s insurance is $1000/year. For the 1st year, your monthly payment will be at 4%. See the chart below for the breakdown.

Run your customized calculation using our buydown mortgage calculator
Understanding 1-0 Buydown Mortgage
A 1-0 buydown mortgage starts at 1% lower than your note rate in year 1. So, if you get a rate of 6%, your first-year monthly payment will be calculated at 5%, and then goes back to your note rate (i.e. 6%) for the rest of the term of the loan.
Let’s look at an example – Say your loan amount is $500,000 at a note rate of 6%. Let’s also assume that the yearly property tax is $7,000 and the homeowner’s insurance is $1000/year. For the 1st year, your monthly payment will be at 3%. See the chart below for the breakdown.

Run your customized calculation using our buydown mortgage calculator
Who Pays for the Difference Between the Expected Payment and the Actual Payment
In the 3-2-1 example, the total buydown is $21,769, for the 2-0 example, the total; buydown is $11,092 and in the 1-0 buydown mortgage example, the total buydown fee is $3,764.
This is the upfront one-time fee that you need to pay to qualify for these loan programs. You should work with your agent to see if you can get the buydown fees paid by the seller. Reviewing these tips for first-time buyers can help you understand how seller-paid buydown fees may reduce your upfront expenses and make the initial mortgage payments more manageable.
That way you can get up to a 3% lower rate in year one without paying any extra closing costs from your pocket.
Why should I choose to go with a Buydown Mortgage?
A buydown mortgage allows you to make a lower monthly payment in the initial year(s). Once the rate goes down, you can refinance into a lower rate anyway. But while the market rates are elevated, you could still make your monthly payments at a lower rate. So, it’s a short-term play while we are waiting for the rates to go down.
With the real estate markets slightly softer than in the last few years, sellers might be more willing to pay you for these discount points as an incentive to get their properties sold. Given the expectations that the rates might go down later this year or early next year, you could consider a 1-0 buydown mortgage thus reducing your upfront cost.
You May Also Like:
- 67
 Calculating an exact mortgage payment in the without a calculator on a loan is no small task, but there are some simple rules-of-thumb you can use to get a close estimate. When coming up with a rough estimate, it is important to understand the individual components that factor into the…
- 54Calculating the net benefit of refinancing can be a challenging task if you do not understand what to calculate. We are going to focus on the net benefits of refinancing from the standpoint of lowering your interest rate. Although there are several reasons to refinance, lowering your mortgage rate to…
- 54
 Understanding the definition of Loan-to-Value (LTV), and how it impacts a mortgage approval, will help you determine what type of loan amount and program you may qualify for If you are evaluating the signs you are ready to buy a house, understanding your potential mortgage eligibility and down payment requirements…



